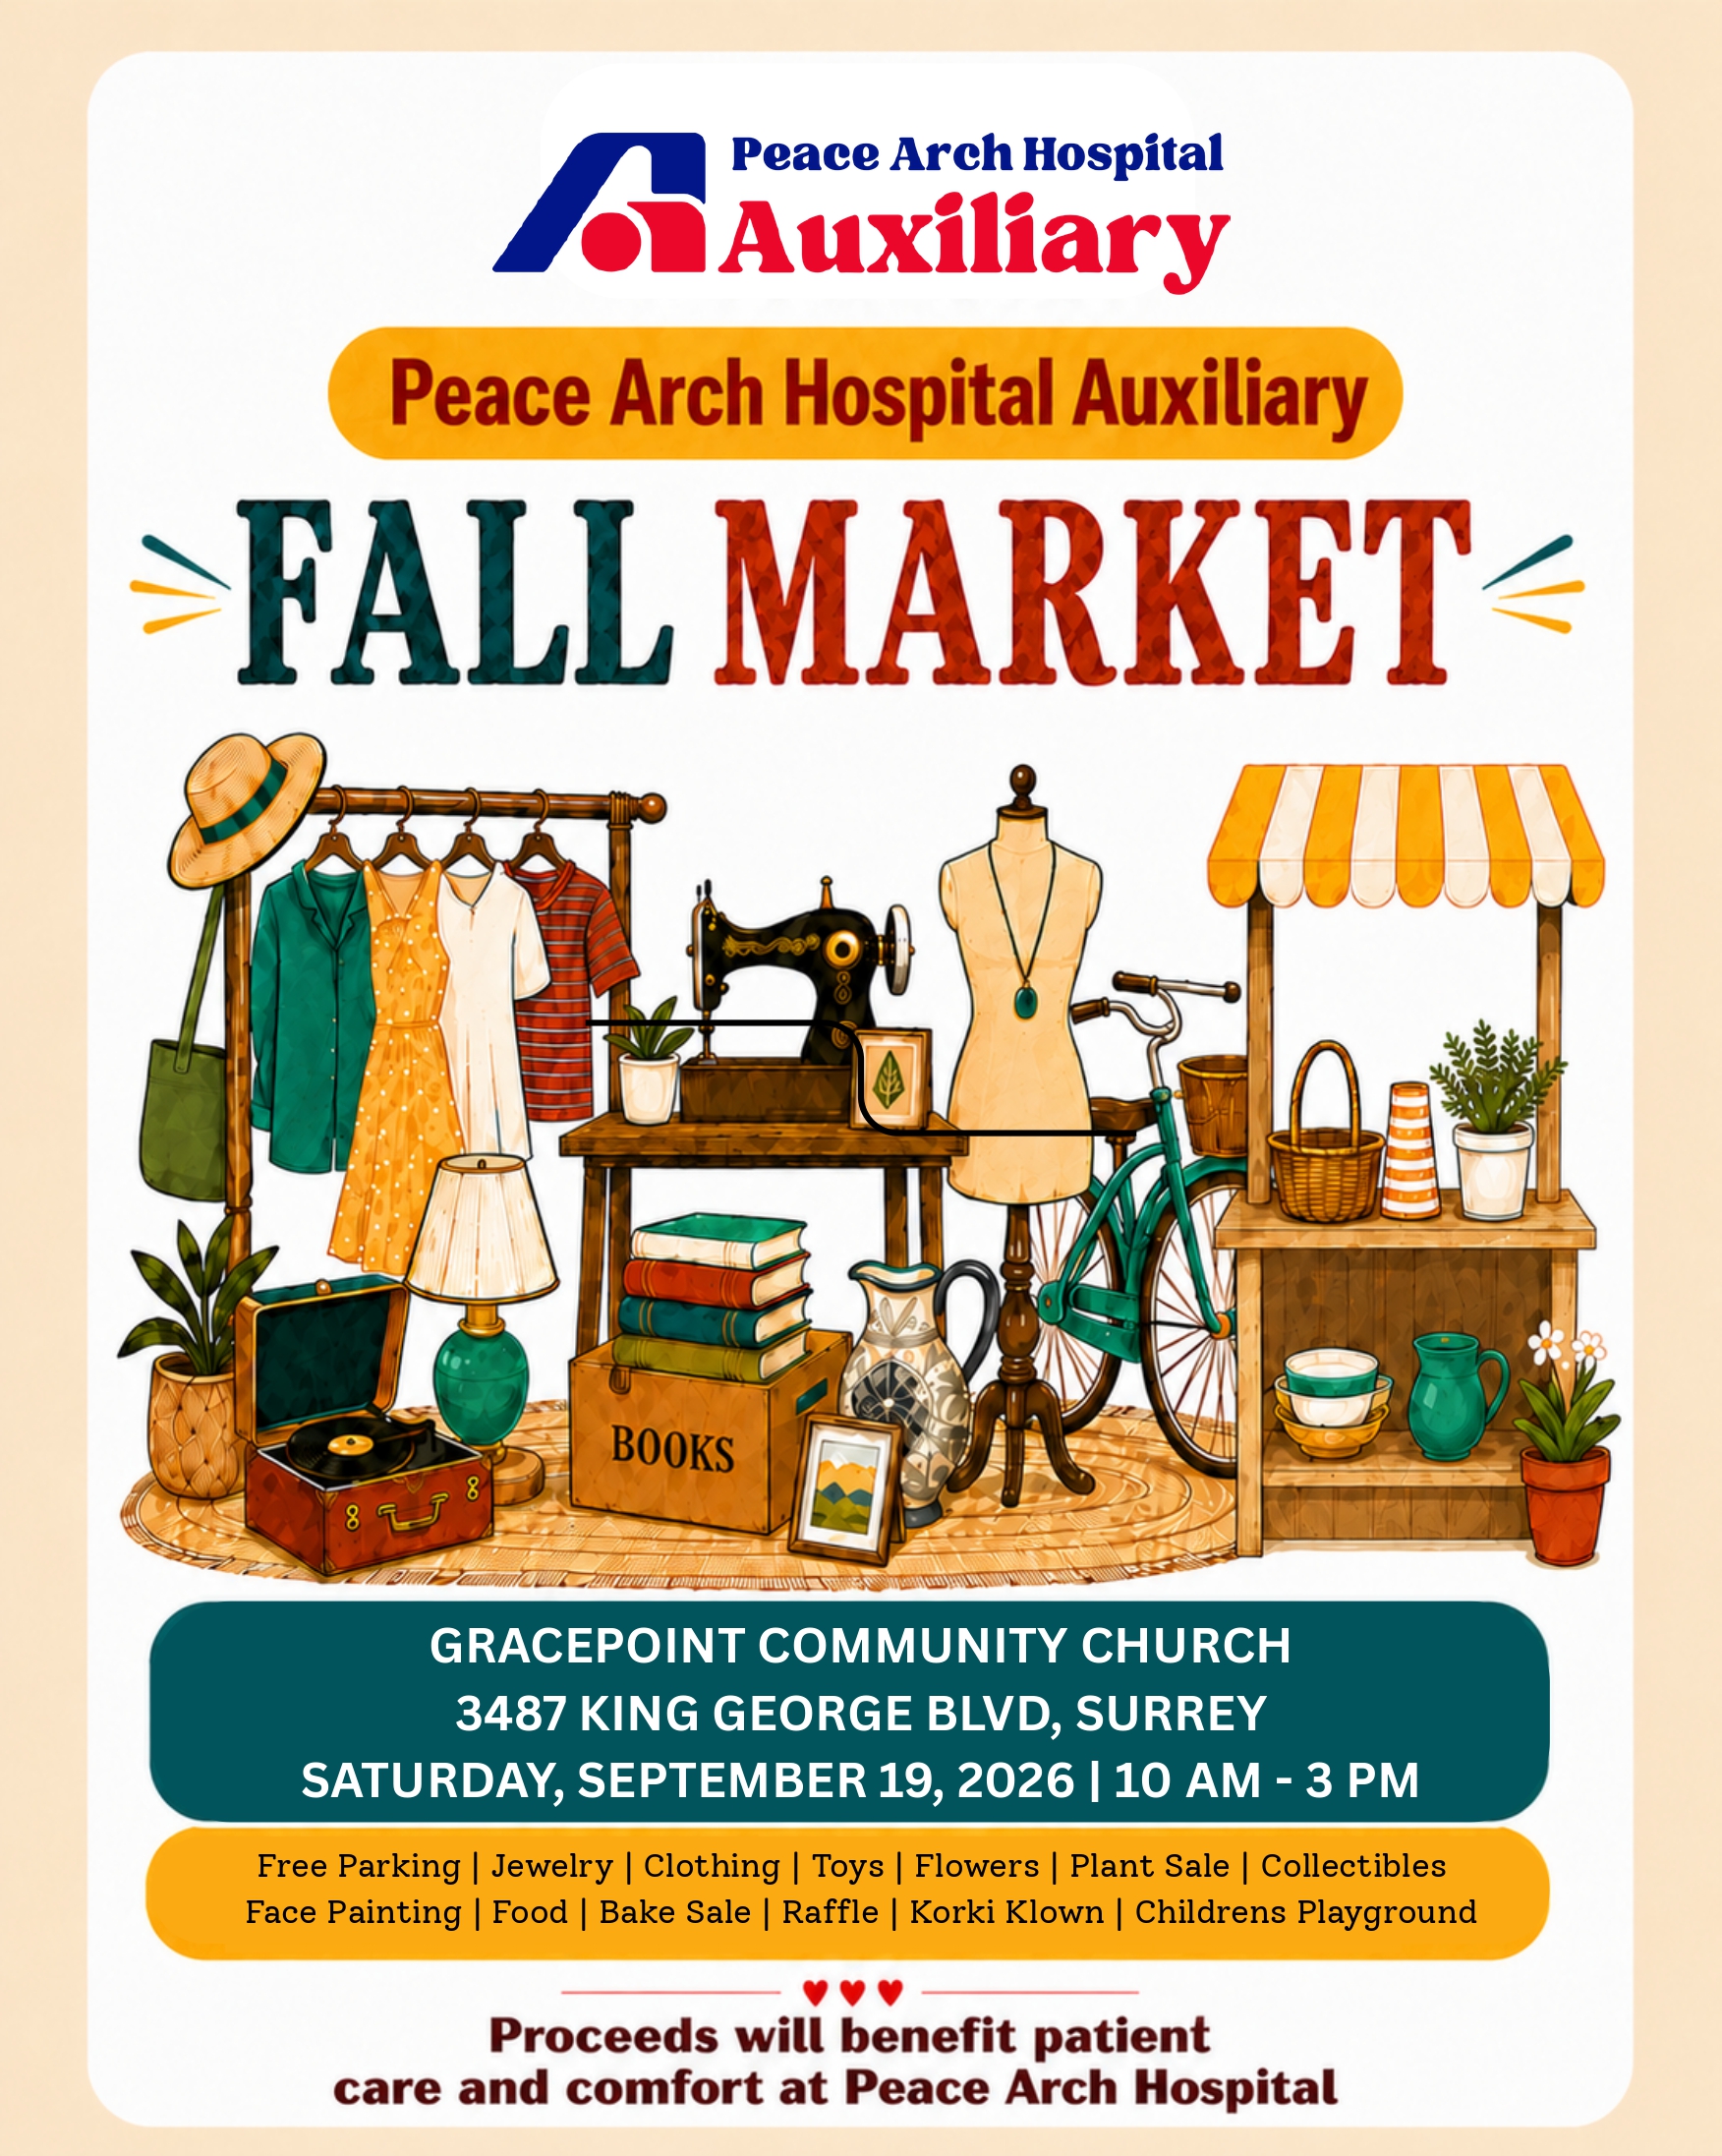
Peace Arch Hospital Auxiliary Fall Market
Yes, we saw another rate hold on Wednesday. In fact, the last rate cut we saw was in October of last year.
So… what’s actually going on?
The Bank is basically saying: “Things are still complicated. Let’s not touch anything until we have a better idea what happens next.”
A few things are keeping them cautious:
Energy prices are elevated, largely because of the ongoing conflict in the Middle East.
Canada and the U.S. are back in tariff/trade-talk drama, with new U.S. tariffs and Canadian counter-measures following the breakdown in negotiations.
The Canadian economy is still dealing with some softness, while inflation has been moving higher. July CPI was 3.0%, although some of the Bank’s preferred underlying inflation measures remain much closer to the 2% range.
What does this mean for your buyers?
The important distinction is that the Bank of Canada controls the overnight rate not the mortgage rates your clients see on a rate sheet.
Variable and adjustable mortgages are directly influenced by the Bank’s policy rate, so today’s decision means no immediate change there.
Fixed mortgage rates are a different animal. They’re influenced much more by bond yields and expectations for where inflation and interest rates are headed. And bond markets, as we know, occasionally enjoy behaving like they’ve had six coffees and no adult supervision. This is where we've seen an up-tick in rates in recent weeks despite no change in prime rate.
The good news for real estate?
For buyers sitting on the fence waiting for “the next rate cut”, today’s announcement is another reminder that waiting for the perfect rate can mean waiting while the house they actually wanted gets sold to someone else.
And for sellers?
Financing conversations matter. A buyer who understands their payment, qualification and available rate options is a much more confident buyer and confidence tends to be good for real estate transactions.
So my takeaway:
Rates are steady. The economy is complicated. The Bank is cautious. And your clients still need a mortgage strategy not a crystal ball.
If you have a buyer wondering whether they should buy now, wait, go fixed, go variable, or simply stare at the Bank of Canada website until it tells them what to do…
With the BC Day long weekend around the corner, I thought I'd touch on a topic that comes up often when homeowners are thinking about moving: mortgage portability.
Many people hear the term "portable mortgage" and assume it means, "Perfect! I'll just pack up, move, and my mortgage comes with me." Easy, right?
Not exactly.
The reality is that porting a mortgage is still an approval process. Even though your clients already have a mortgage, they'll need to re-qualify for the mortgage amount based on their current financial situation. The lender will also need to approve the new property they're purchasing. In other words, it's not an automatic "yes."
Here's another interesting point that often catches people by surprise:
If your client has their mortgage with a credit union, there may be geographic lending restrictions. Some credit unions don't lend outside their home province, and others may only lend within certain regions of BC. That can impact whether a mortgage can actually be ported to the new property.
And here's something else worth considering...
Porting isn't always the best financial option.
Depending on today's interest rates, it may actually make more sense to break the existing mortgage if current market rates are lower than the client's current rate, even after factoring in any penalties. In some cases, a lender may also offer a blend-and-extend option, which combines the client's existing rate with today's market rate and extends the mortgage into a new term.
Every situation is different, which is why it's so important to review all of the options before making a decision.
So, if you or your clients are thinking about moving and wondering whether porting their mortgage is the right choice, I'd be happy to walk through what it really means and help determine the best path forward.
Wishing you all a fantastic BC Day long weekend! I hope you get a chance to relax, recharge, and enjoy some well-deserved time with family and friends.
What does that mean in plain English? For now, borrowing costs aren't changing, which is good news for buyers who have been waiting for more stability.
The Bank is feeling a little more optimistic about the economy, but they're still keeping a close eye on inflation before making any future rate changes. While no one can predict exactly what will happen next, Wednesday's announcement gives buyers and sellers a bit more confidence as they plan their next move.
One thing I did want to note is that in the past two rate decisions, Macklem had warned that “consecutive” rate hikes might be needed if the Middle East conflict continues and higher energy prices feed into broader inflation. He dropped this language in Wednesday’s opening remarks, along with a warning that there may be a need to cut if the U.S. imposes major new trade restrictions.
You're Invited – Lunch & Learn!
I'd love for you to join us on Thursday, July 23 for a fun and informative Lunch & Learn at 10 AM followed by a lunch at 12 PM (ish!).
I'll be sharing:
Pre-Approval Do's & Don'ts – how to avoid common mistakes and help your clients put their best foot forward.
Mary Mendoza Festejo - Financial Advisor - will also be presenting:
Practical financial tips that can help your clients prepare for homeownership and strengthen their financial position.
As we head into the weekend, all eyes are on next Wednesday's Bank of Canada rate announcement. The question everyone is asking is: Will they cut, hold, or surprise us?
The current consensus among economists is that the Bank of Canada will hold the overnight rate steady, with many expecting borrowing costs to remain relatively unchanged for the rest of 2026. Of course, as we've learned over the past few years, markets can change quickly, and global events continue to play a significant role in where rates ultimately head.
I'll leave the forecasting to the economists (Brendon, I'm looking at you!), but one thing I am keeping a close eye on is the bond market.
For buyers considering a fixed-rate mortgage, there are still lenders offering insured 3- to 5-year fixed rates with a 3 in front. If your clients qualify, now may be an excellent time to secure those rates before they're gone.
A simple way to think about it:
War on = Bond yields up = Fixed rates up
War off = Bond yields down = Fixed rates down
Geopolitical uncertainty has a direct impact on bond yields, and fixed mortgage rates tend to follow. Timing the market is never easy, but if your clients are actively shopping, locking in today's rates could provide valuable peace of mind.
As always, I'll send out an update as soon as the Bank of Canada makes its announcement next Wednesday, along with what it means for your buyers and sellers.
If you have clients with questions this week or anyone who would benefit from getting pre-approved before making an offer don't hesitate to reach out. I'm always happy to help.
1. Consider gifting to the child only—not the couple
When parents are providing down payment funds, the gift letter can name their child as the recipient rather than both partners.
Why does this matter?
While nobody is thinking about relationship breakdowns when purchasing a home, I can tell you from my experience helping clients through separation and divorce that how a gift is documented can become very important years later. A gift made specifically to one individual may provide a stronger position if ownership or family property issues ever arise down the road.
From a lender's perspective, this distinction generally doesn't impact the mortgage approval process. However, it could matter significantly to the family later.
2. For larger gifts, encourage families to document their intentions
If parents are contributing a substantial amount, it may be worth suggesting they speak with a family lawyer about documenting their intentions separately from the mortgage process.
Questions might include:
Is this truly an unconditional gift?
Is there any expectation the funds would return to the family in the event of separation or death?
Are there other family considerations that should be addressed?
A simple agreement prepared while everyone is on good terms can provide clarity and potentially save significant legal costs and family conflict in the future.
Why This Matters
One trend family law professionals continue to discuss is that courts generally look at documentation created at the time the money changes hands. In other words, it's difficult to argue years later that a gift was actually intended to be something else if there is no supporting documentation.
For mortgage purposes, gifted funds must be non-repayable and lenders require gift letters to clearly state this. Any family-law agreement would be completely separate from the mortgage file and would not change how the gift is presented to the lender.
A Quick Disclaimer
As a mortgage professional I am not a lawyer and I don't provide legal advice. My role is simply to raise awareness so clients can seek proper legal guidance if they feel it's appropriate for their situation.
Nobody expects separation, divorce, or estate issues when buying a home together. That's exactly why these conversations are often most valuable at the beginning of the process, when everyone is aligned and working toward the same goal.
A quick reminder that BC property taxes are due by July 2, so now is a great time to encourage clients to review their payment plans and grant eligibility early.
Here are a few important conversations worth having with homeowners right now:
Home Owner Grant (HOG) & Senior Grant
Eligible clients could save $570+ simply by applying. Many homeowners still assume this is automatic. It’s not.
Property Tax Deferment Changes in BC
As of this year, deferment qualification rules and options have changed. Some homeowners may no longer qualify under the same terms, while others may want to reconsider whether deferment is still the best long-term strategy.
Equity & Cash Flow Planning Opportunities
For certain clients, especially retirees or homeowners managing rising costs it may make more sense to explore an equity take-out strategy such as:
• Reverse mortgages
• HELOC restructuring
• Refinancing options
• Equity preservation planning
These conversations can create huge value for your clients while also opening the door to future purchase, downsizing, and wealth-planning opportunities.
Also, for any clients buying or selling before July 2, make sure they speak with their lawyer or conveyancer early regarding who will be responsible for property taxes and grant applications on completion.
If you have clients wondering whether property tax deferment or accessing equity makes more sense for their situation, I’m always happy to jump on a strategy call and help you navigate the options.

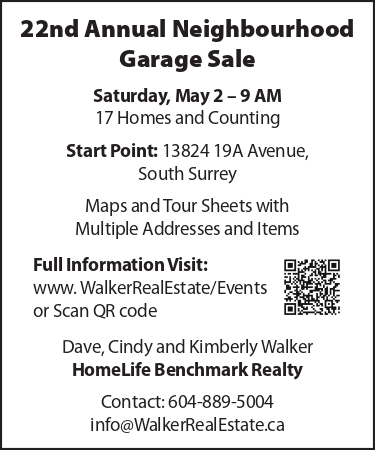
22nd Annual Neighbourhood Garage Sale on Saturday, May 2nd Compliments of Dave, Cindy and Kimberly Walker, HomeLife Benchmark Realty! 17 homes this year, including Peace Arch Hospital Auxiliary in Walker Driveway raising over $2300.00 toward comfort care and machines. The Weinart family once again organized the Crescent United Church in their driveway raising $890.00 with a number of dollars accolated toward Ray Shepherd School Back-Pack Buddies Program supporting over 18 families! Great weather and all sellers did well selling their merchandise! All in all a successful day!
Key takeaways you should know:
This marks another hold in 2026, as the Bank continues to wait for clearer economic direction.
Inflation has ticked up recently (largely due to energy prices), but remains relatively controlled.
Ongoing global uncertainty (Middle East conflict, trade/tariffs) is a major reason for the cautious stance.
The Bank signaled that future rate moves could go either way, but if things track as expected, changes should be gradual.
Bottom line:
Rates holding steady keeps variable-rate borrowers stable for now, but the door is still open for potential increases later this year depending on inflation.
Quick Spotlight: What is Alternative Lending (Why it matters for your clients)
What is alternative lending?
Alternative (or “B” / private) lending provides mortgage solutions outside of the major banks, often with more flexible qualification criteria.
These lenders look beyond strict income and credit guidelines focusing more on equity, overall financial picture, and the story behind the file.
Who does it help?
Self-employed clients with write-offs
Clients with bruised or limited credit
Those between jobs or income transitions
Buyers who just don’t fit the bank “box” (increasingly common)
Why it’s on the rise:
Tighter bank rules + stress test challenges are pushing more borrowers out of prime lending
Growth of “near-prime” borrowers - strong clients who simply don’t meet rigid bank criteria
Economic uncertainty is making income qualification harder for many Canadians
How it benefits your clients:
Keeps deals alive when banks decline
Provides short-term bridge solutions (typically 6–24 months) to get clients back to prime lending
Offers flexibility to restructure, consolidate debt, or stabilize finances
Alternative lending isn’t a last resort anymore. It’s a strategic tool when used correctly, with a clear exit plan.

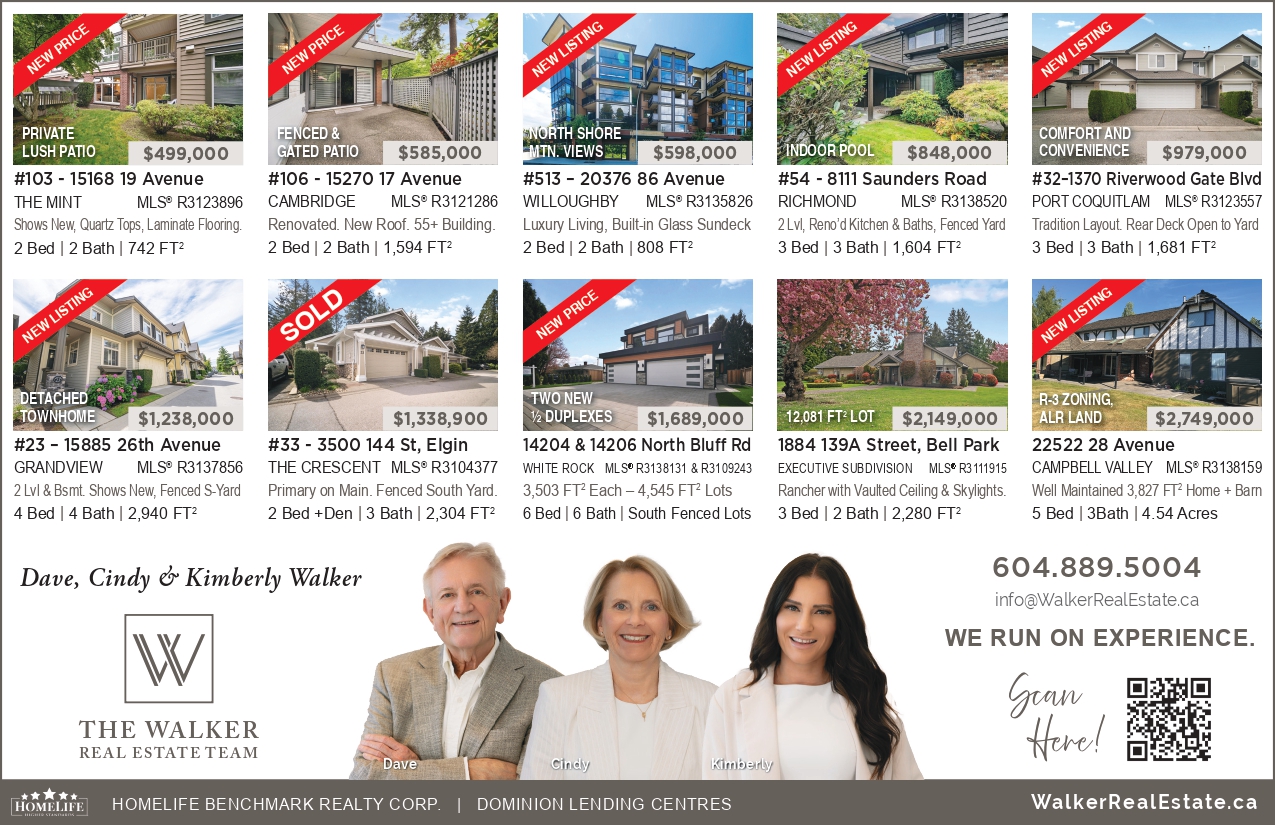
Your Trusted Partner in Real Estate. Contact us at 604-889-5004 for all your property needs.
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.